Mutual funds can grow your wealth, but taxes can quietly reduce what you keep. Every time you sell fund shares at a profit, or your fund passes gains to you, the IRS may take a share. The good news is that several legal strategies can reduce capital gains tax on mutual funds. This guide explains how the tax works, seven practical ways to lower it, how to calculate your bill, and what to review before December 31, 2026. Everything is explained in simple, easy language, so you can plan with confidence and keep more of your hard-earned investment returns.
What Is Capital Gains Tax?
Capital gains tax is the tax you pay on profit when you sell an investment for more than you paid. With mutual funds, you can owe it in two ways: when you sell your shares, and when the fund sells holdings and passes the gains to you as a distribution. Your gain is the sale price minus your cost basis, which is what you paid, including reinvested dividends. How long you held the investment decides your tax rate. Understanding this basic rule is the first step to lowering your bill.
Types of Capital Gains
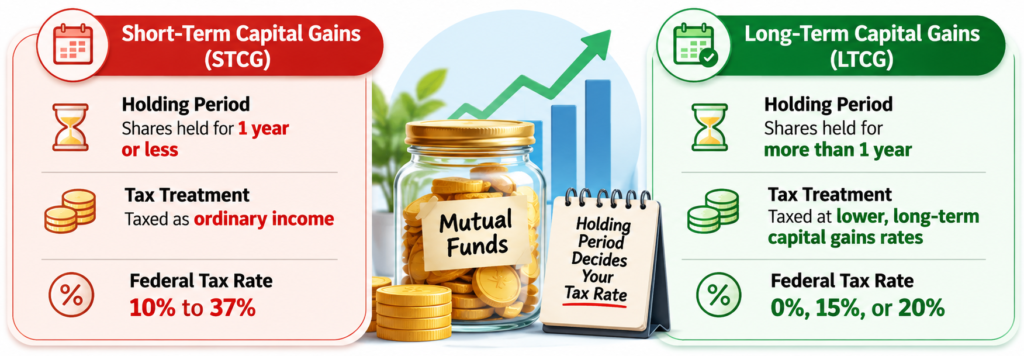
1. Short-Term Capital Gains (STCG)
Profit on shares held one year or less. It is taxed as ordinary income, at rates from 10% to 37%.
2. Long-Term Capital Gains (LTCG)
Profit on shares held more than one year. It is taxed at lower federal rates of 0%, 15%, or 20%.
Tax Implications on Mutual Fund Investments
| Situation | How It Is Taxed | What to Know |
|---|---|---|
| Sell shares held 1 year or less | Ordinary income rates (10%–37%) | The most expensive way to sell |
| Sell shares held more than 1 year | 0%, 15%, or 20% | Rate depends on your taxable income |
| Short-term capital gain distribution | Ordinary income rates | Taxable even if you reinvest it |
| Long-term capital gain distribution | 0%, 15%, or 20% | Treated as long-term, no matter how long you own the fund |
| Qualified dividends | 0%, 15%, or 20% | Same rates as long-term gains |
| Ordinary (non-qualified) dividends | Ordinary income rates | Reported on Form 1099-DIV |
| 2026 LTCG 0% bracket | Taxable income up to $49,450 (single) or $98,900 (joint) | 20% applies above $545,500 (single) or $613,700 (joint) |
| High-income investors | Extra 3.8% Net Investment Income Tax | Applies when MAGI is above $200,000 (single) or $250,000 (joint) |
| Funds inside a 401(k) or IRA | No yearly capital gains tax | Tax is paid at withdrawal (Roth: generally tax-free) |
7 Legal Ways to Reduce Capital Gains Tax on Mutual Funds
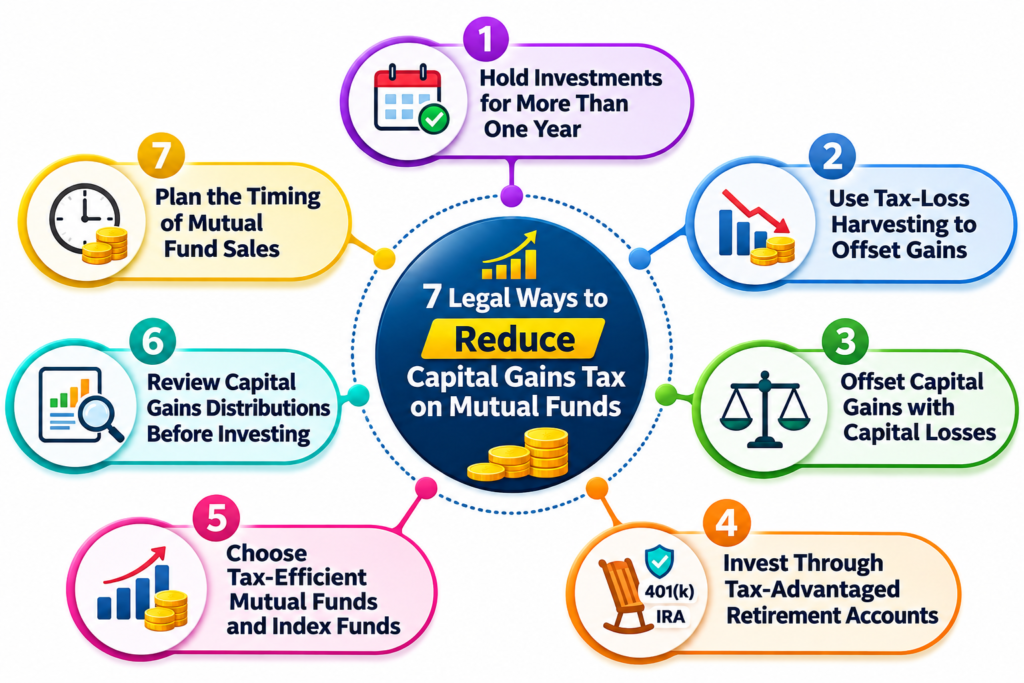
1. Hold Mutual Fund Investments for More Than One Year
Selling after holding shares for more than one year moves your gain from ordinary income rates, up to 37%, to long-term rates of 0%, 15%, or 20%. Check your purchase date before you sell. Waiting a few extra days can cut your federal tax sharply.
2. Use Tax-Loss Harvesting to Offset Capital Gains
Tax-loss harvesting means selling an investment at a loss to cancel out gains elsewhere. You can then buy a similar, but not identical, fund to stay invested. Avoid the wash sale rule, which disallows the loss if you rebuy the same fund within 30 days.
3. Offset Capital Gains with Capital Losses
Capital losses first cancel gains of the same type, then the other type. If losses exceed gains, you can deduct up to $3,000 against ordinary income each year ($1,500 if married filing separately). Any extra loss carries forward to future years with no expiry date.
4. Invest Through Tax-Advantaged Retirement Accounts
Mutual funds held in a 401(k), traditional IRA, or Roth IRA avoid yearly capital gains tax. For 2026, you can contribute up to $24,500 to a 401(k) and $7,500 to an IRA. Business owners can also explore these small business tax-saving strategies for extra savings.
5. Choose Tax-Efficient Mutual Funds and Index Funds
Index funds and ETFs trade less often, so they usually pass fewer taxable gains to investors. Actively managed funds may distribute more. Lower fund costs also help you keep more returns. If you also invest globally, compare GIFT City funds and international ETFs before choosing.
6. Review Mutual Fund Capital Gains Distributions Before Investing
Funds usually pay capital gains distributions near year-end. If you buy just before the record date in a taxable account, you may owe tax on gains you never earned. Check the fund’s distribution schedule first. This simple check can prevent a surprise December tax bill.
7. Plan the Timing of Mutual Fund Sales
Spread large sales across several tax years, or sell in a year when your income is lower, to stay in a lower bracket. Choose specific shares, not average cost. You can also read when NRIs should sell Indian mutual funds after moving to the USA.
How to Calculate Capital Gains Tax on Mutual Funds?
- Find your cost basis: shares bought multiplied by price paid, plus any fees and reinvested dividends.
- Find your sale proceeds: shares sold multiplied by the price (NAV) on the sale date.
- Calculate the gain or loss: sale proceeds minus cost basis.
- Check your holding period: one year or less is short-term; more than one year is long-term.
- Net your gains and losses: match short-term with short-term and long-term with long-term, then combine the results.
- Apply the tax rate: use ordinary income rates for short-term gains and 0%, 15%, or 20% for long-term gains.
- Add the 3.8% NIIT if it applies: check whether your MAGI is above $200,000 (single) or $250,000 (joint).
- Report it: use Form 1099-B, Form 8949, and Schedule D.
Example: Sam sells 200 fund shares at $60 each. His cost basis is $8,000.
| Item | Held 1 Year or Less | Held More Than 1 Year |
|---|---|---|
| Sale proceeds (200 × $60) | $12,000 | $12,000 |
| Cost basis | $8,000 | $8,000 |
| Capital gain | $4,000 | $4,000 |
| Assumed tax rate | 24% (ordinary) | 15% (long-term) |
| Federal tax owed | $960 | $600 |
Rates are for illustration. State tax and NIIT may apply on top.
Year-End Mutual Fund Tax Planning: What to Review Before December 31, 2026
Want more December 31 tasks? See this year-end tax planning guide.
Review Your Realized Capital Gains and Losses
Check your brokerage account for gains and losses realized so far in 2026. This shows your likely tax bill.
Identify Investments for Tax-Loss Harvesting
Look for funds trading below your cost basis. Selling them before year-end can offset gains and reduce your tax bill.
Check Upcoming Mutual Fund Distributions
Ask your fund company for estimated year-end distributions. Avoid buying right before payout dates in taxable accounts to avoid surprises.
Review Your Tax-Loss Carryforwards
Check last year’s return for unused capital losses. Carryforward losses can offset this year’s gains and lower your tax bill.
Organize Brokerage Tax Documents
Gather cost basis records, trade confirmations, and prior statements now, so Forms 1099-B and 1099-DIV are easy to verify.
Common Mistakes to Avoid When Reducing Mutual Fund Taxes
Mistake 1: Selling Just Before the One-Year Mark
Selling a few days early can turn a long-term gain into a short-term gain taxed at much higher rates.
Mistake 2: Triggering the Wash Sale Rule
Rebuying the same or a very similar fund within 30 days, even in an IRA, can disallow your harvested loss.
Mistake 3: Buying Right Before a Distribution
Investing just before a capital gains payout in a taxable account creates a tax bill for gains you never earned.
Mistake 4: Ignoring Foreign Mutual Fund Rules
Indian mutual funds held from the US face PFIC rules and Form 8621 reporting, which can mean harsher tax.
Conclusion
Reducing capital gains tax on mutual funds comes down to smart habits: hold investments longer, use losses wisely, favor tax-efficient funds, and use retirement accounts. Review your gains, losses, and expected distributions before December 31, 2026, and keep clean records for your tax return. Small decisions made now can save real money later, so start with just one strategy today. Tax rules and limits change, so confirm current figures with the IRS or a qualified tax professional before you act
Disclaimer
The content published on NriTaxs is intended for informational purposes only and does not constitute legal, tax, or financial advice. Readers are encouraged to consult qualified professionals before making any decisions based on the information provided.


Related Articles