If you’ve recently moved abroad, or you’re planning to, one question comes up again and again: am I officially an NRI yet, and what does that actually change? The term gets used loosely in everyday conversation, but under Indian law it has a precise meaning with real consequences: how your income is taxed, which bank accounts you’re allowed to hold, where you can invest, and which forms you need to file. Getting this wrong isn’t just a technicality; it can mean paying tax you didn’t need to, or missing a filing you did. This guide breaks down exactly who is an NRI, how your status is decided, and what it means for your money.
Key Takeaways
- ✔ NRI status depends on residential rules.
- NRI status is determined based on an individual’s stay in India and applicable residential-status rules for the financial year.
- ✔ NRIs can open specialised bank accounts.
- NRIs can use NRE, NRO, and FCNR accounts to manage foreign earnings, Indian income, savings, and investments.
- ✔ NRIs can invest in India.
- NRIs can invest in permitted options such as mutual funds, shares, fixed deposits, and property, subject to applicable rules.
- ✔ NRI tax depends on Indian income.
- Income earned or received from Indian sources, including rent, interest, dividends, and capital gains, may be taxable in India.
What Does NRI Mean & Its Full Form?
Let’s first understand the meaning and full form of NRI.
NRI Full Form
NRI stands for Non-Resident Indian. It refers to an Indian citizen who lives outside India for work, business, education, or any other purpose that keeps them abroad for a certain period of time during a financial year.
NRI Meaning
Simply put, an NRI is someone who holds Indian citizenship but doesn’t meet the physical-stay conditions to be treated as a “resident” of India under Indian tax law. Your passport status doesn’t decide the number of days you’ve actually spent in India.
Eligibility Criteria for NRIs
- Indian Citizenship:- You must be an Indian citizen (or a Person of Indian Origin, in some contexts) to be classified as an NRI. Foreign nationals living abroad obviously don’t fall under this category at all.
- Period of Stay:- Your residential status depends mainly on how many days you’ve stayed in India during the financial year, and sometimes in the years before that. Spend too little time in India, and you qualify as a non-resident.
- Purpose of Stay:- Why you’re abroad also matters in certain cases for employment, business, or an uncertain-duration stay. This purpose can affect which day-count rule applies to you, especially for Indian citizens leaving India for work.
Types of NRI Bank Accounts
Non-Resident External (NRE) Account
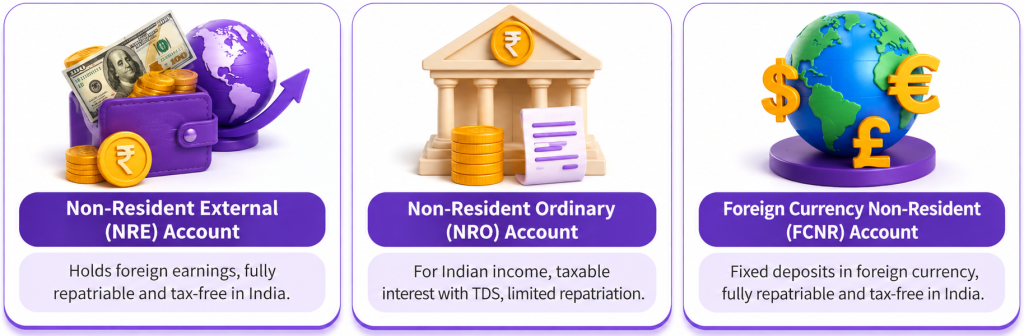
An NRE account holds your foreign earnings after converting them to Indian rupees. Both the principal and interest are fully repatriable, and the interest earned is tax-free in India for as long as your NRI status continues. If you’re deciding between account types, this detailed comparison of NRE vs NRO accounts breaks down which one fits your situation.
Non-Resident Ordinary (NRO) Account
An NRO account is meant for income earned within India rent, dividends, or pension, for example. Repatriation is allowed but limited, and interest earned here is taxable, with TDS deducted before it’s credited.
Foreign Currency Non-Resident (FCNR) Account
An FCNR account lets you hold a fixed deposit in a foreign currency itself, avoiding currency-conversion risk entirely. It’s fully repatriable, and the interest is tax-free in India, making it popular for long-term NRI savings.
NRO vs. NRE vs. FCNR at a Glance
| Feature | NRE Account | NRO Account | FCNR Account |
| Currency held | Indian Rupees | Indian Rupees | Foreign currency |
| Source of funds | Foreign income | Indian income | Foreign income |
| Repatriability | Fully repatriable | Limited, subject to conditions | Fully repatriable |
| Taxability of interest | Tax-free in India | Taxable, with TDS | Tax-free in India |
| Account type | Savings/current | Savings/current | Fixed deposit only |
Benefits of NRI Accounts
- Tax-Free Earnings:- Interest earned in NRE and FCNR accounts is exempt from Indian income tax, which helps your savings grow faster compared to a taxable Indian account.
- Full Repatriability:- Funds in NRE and FCNR accounts can be moved abroad freely, without the repatriation limits and extra paperwork that apply to NRO account balances.
- Investment Opportunities:- These accounts act as the gateway for NRIs to invest in Indian mutual funds, fixed deposits, stocks, and other instruments, all from outside India.
- Convenient Banking Services:- Most banks now offer full online access, international debit cards, and dedicated NRI service desks, so you can manage your money without visiting India.
- Protection From Currency Fluctuations:- An FCNR deposit, held in a foreign currency, shields your savings from rupee depreciation, since you aren’t converting your money back and forth.
How to Open an NRI Account?
Choose the Right Type of Account
Decide between NRE, NRO, or FCNR based on where your income comes from and whether you want to hold rupees or a foreign currency. Most NRIs end up opening more than one.
Gather Required Documents
You’ll typically need your passport, visa or work permit, overseas address proof, PAN card, photographs, and an NRI account-opening form provided by the bank.
Submit Application Online or Offline
Many Indian banks now allow NRIs to open accounts fully online through video KYC, though some still require documents to be couriered or submitted at a branch.
Fund the Account
Once approved, you fund the account with an initial deposit typically a wire transfer from your overseas bank account to activate it.
Activate and Manage the Account
After activation, you can manage the account through net banking or a mobile app, set up standing instructions, and link it to your investments in India.
Who Is Considered a Non-Resident for Indian Tax Purposes?
For Indian tax purposes, you’re treated as a non-resident if you don’t meet the minimum physical-presence conditions laid down under the Income Tax Act for a “resident.” This is decided fresh every financial year based on your actual travel record, not on your visa type, your intention to settle abroad, or how long you’ve already been away. Even someone who has lived abroad for a decade can technically become a “resident” again for one year if they spend enough time in India that year, so this status needs to be checked annually rather than assumed.
NRI Definition as per the Income Tax Act of India
The Income Tax Act doesn’t define “NRI” directly; instead, it defines who is a “resident,” and anyone who doesn’t meet those conditions is automatically a non-resident.
| Condition | Classified As |
| Stayed in India for 182 days or more in the financial year | Resident |
| Stayed 60 days or more in the financial year AND 365 days or more in the preceding 4 years | Resident (general rule) |
| Indian citizen leaving India for employment/business abroad — the 60-day rule is relaxed to 182 days | Non-Resident (if under 182 days) |
| Doesn’t meet any of the above conditions | Non-Resident Indian (NRI) |
How Is NRI Residential Status Determined?
Resident vs Non-Resident
Your status is a binary test applied every financial year: either you satisfy the minimum-stay conditions and are treated as a resident, or you don’t and are treated as a non-resident for that year.
Number of Days Stayed in India
The basic test counts how many days you were physically present in India during the current financial year, generally 182 days is the key threshold most NRIs track closely. Once you’ve worked out your status, it’s worth knowing how to update your residential status on the income tax portal, since an outdated record there can cause TDS and filing mismatches.
Previous Years’ Stay
A second test also looks at your total stay over the four years before the current one, which can pull you into “resident” status even with a shorter stay in the current year.
Special Rules for Indian Citizens Leaving India
If you’re an Indian citizen leaving the country for employment or as a crew member, the usual 60-day trigger is relaxed to 182 days, giving you more flexibility to visit India without affecting your NRI status.
Deemed Resident Rules
An Indian citizen with total Indian income above ₹15 lakh who isn’t liable to tax in any other country can be treated as a “deemed resident,” even without meeting the usual day-count conditions.
What Is RNOR?
RNOR stands for Resident but Not Ordinarily Resident. It’s a transitional status, usually applying for one or two years right after you return to India permanently. In this phase, your foreign income generally stays untaxed in India, even though you’re technically a “resident” again. It exists to give returning NRIs a buffer period before full resident taxation applies to their worldwide income.
How Does Tax Residential Status Differ From FEMA Status?
These two statuses are decided differently and can genuinely give you different answers at the same time. Your income tax residential status is worked out purely from your physical-presence count during the financial year, recalculated every single year. Your FEMA (banking and foreign exchange) status, on the other hand, changes the moment your purpose and intention of stay shifts for instance, the day you leave India for a job abroad, you become an NRI under FEMA immediately, even though your tax residential status for that same year might still technically work out as “resident” based on the days you’d already spent in India. This mismatch is exactly why some NRIs end up using the wrong bank account type or the wrong ITR form.
Income Tax vs FEMA — Key Differences
| Aspect | Income Tax Residential Status | FEMA Residential Status |
| Based on | Number of days stayed in India | Purpose and intention of stay |
| Reviewed | Freshly every financial year | Changes immediately when purpose changes |
| Governs | Tax liability, ITR filing | Bank accounts, investments, repatriation |
| Regulator | Income Tax Department | Reserve Bank of India (RBI) |
Financial and Tax Implications for NRIs
Income Tax Liability
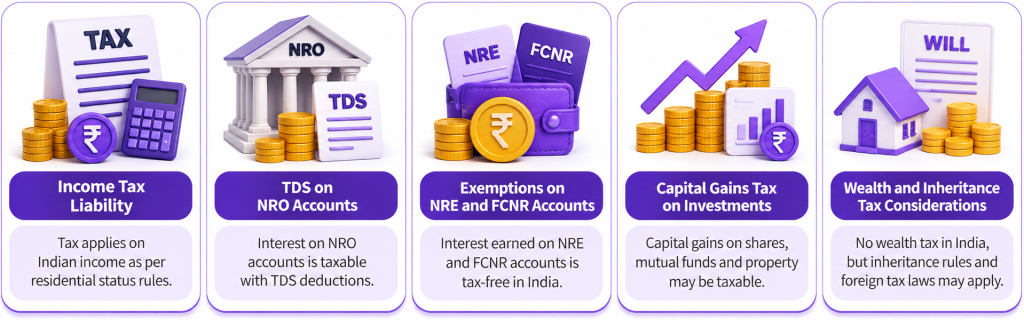
NRIs are taxed only on income earned or received in India rent, capital gains, interest, and similar sources not on income earned abroad, which stays outside the scope of Indian tax entirely. The exact slabs and rates that apply are laid out in this guide to NRI tax slab rates for 2026-27.
TDS on NRO Accounts
Interest credited to an NRO account has TDS deducted at source before you receive it, generally at a higher rate than what applies to resident account holders.
Exemptions on NRE and FCNR Accounts
Interest earned in NRE and FCNR accounts remains exempt from Indian income tax for as long as you continue to qualify as an NRI, which is a major reason these accounts are popular for parking savings.
Capital Gains Tax on Investments
Selling property, shares, or mutual fund units in India triggers capital gains tax, with the rate depending on the asset type and how long you held it before selling. If shares are part of your portfolio, this breakdown of NRI capital gains tax on shares covers the rates and TDS involved, while property sales follow their own updated NRI property TDS rules.
Wealth and Inheritance Tax Considerations
India currently has no wealth tax or inheritance tax, so inheriting Indian assets as an NRI doesn’t by itself create a tax bill though selling the inherited asset later does.
What Happens to Your Indian Bank Accounts After Moving Abroad?
The moment your residential status changes, your existing resident savings account is technically supposed to stop being operated as a regular resident account. In practice, you need to inform your bank and get it converted into an NRO account, since continuing to run a resident account as an NRI is a FEMA violation, even if the bank hasn’t flagged it yet. Any salary or passive Indian income rent, dividends, pension should then route through this NRO account going forward. If you also start remitting foreign earnings to India, that’s where a separate NRE account comes in, and funds between the two move under specific, documented rules rather than freely the current NRO to NRE transfer limits are worth checking before you move any large amount.
What Should NRIs Do After Moving Abroad?
- Check Your Residential Status
Determine whether you qualify as an NRI based on your stay in India and applicable income tax residential-status rules. - Update Your Bank Accounts
Inform your bank about your residential-status change and redesignate resident savings accounts as NRO accounts where required. - Update PAN & KYC Details
Update your overseas address, contact information and residential status with banks, brokers, mutual funds and other financial institutions. - Review Your Tax Obligations
Identify your Indian income, including rent, interest, dividends and capital gains, and check applicable TDS and ITR requirements. - Review Your Investments
Check whether your existing mutual funds, stocks, deposits or other investments require updated KYC, documentation or compliance after becoming an NRI. - Check DTAA Benefits
If you become a tax resident of another country, review the India–country DTAA to understand applicable tax relief and foreign tax credit provisions. - Maintain Important Documents
Keep your passport, overseas address proof, PAN, bank records, tax documents and investment statements updated and securely maintained.
Where NRIs Can & Cannot Invest
Where NRIs Can Invest
- Mutual funds through NRE/NRO accounts, subject to the fund house’s country-specific restrictions.
- Listed shares via the Portfolio Investment Scheme (PIS) or NRO non-PIS route.
- Fixed deposits NRE, NRO, and FCNR.
- Residential and commercial real estate (excluding certain restricted categories).
- Life insurance and select government bonds.
- GIFT City investment products in foreign currency.
Where NRIs Cannot Invest
- Agricultural land, plantation property, or farmhouses.
- New Public Provident Fund (PPF) or National Savings Certificate (NSC) accounts.
- Certain small savings schemes restricted to resident Indians
- Chit funds and a handful of sector-restricted equity categories beyond prescribed foreign investment limits.
Important Guidelines for NRIs
- Maintain Appropriate Bank Accounts:- Keep your accounts correctly classified as NRE, NRO, or FCNR rather than continuing to operate an old resident account after your status changes.
- Update Residential Status Regularly:- Review your residential status every financial year, since travel patterns can shift it even if your life circumstances haven’t changed much.
- Understand Taxation Rules:- Know which income is taxable in India and which isn’t, so you don’t overpay tax on foreign income or underreport Indian-sourced income.
- Check Investment Eligibility Before Investing:-Confirm an investment option is actually open to NRIs before committing funds, since some resident-only products can create compliance headaches later.
- Keep KYC and Documents Updated:- Refresh your KYC with banks, brokers, and mutual funds whenever your address, passport, or residential status changes to avoid frozen accounts.
Conclusion
Being an NRI isn’t just about living outside India it’s a status defined by specific day-count rules, reassessed every year, that determines your tax liability, your banking options, and where you can invest. Getting your residential status right, keeping your accounts correctly classified, and staying current on KYC requirements protects you from compliance trouble and unnecessary tax. When in doubt about where you stand, it’s worth double-checking your status before the financial year ends rather than after.
Disclaimer
The content published on NriTaxs is intended for informational purposes only and does not constitute legal, tax, or financial advice. Readers are encouraged to consult qualified professionals before making any decisions based on the information provided.
Related Articles