Moving back to India with a 401(k)? Don’t withdraw it just because you’re leaving the U.S. A withdrawal can trigger U.S. taxes, a 10% early-distribution penalty in some cases, and additional Indian tax and reporting considerations. The bigger question is: Should you keep your 401(k), roll it into an IRA, withdraw it gradually, or consider your RNOR window before taking distributions? For NRIs returning to India, the answer depends on your age, 401(k) plan rules, U.S. tax status, and Indian residential status. This guide breaks down your options and the key tax checks to make before you touch your 401(k).
Key Takeaways
- ✔ Moving back to India does not mean you need to withdraw your 401(k) immediately.
- ✔ You can keep your 401(k), roll it over to a Traditional IRA, take periodic withdrawals, or withdraw the balance as a lump sum.
- ✔ Your RNOR/ROR status can significantly affect the Indian tax treatment of your 401(k) decisions.
- ✔ Withdrawals before age 59½ may trigger a 10% early-distribution penalty unless an exception applies.
- ✔ A direct 401(k)-to-IRA rollover can generally avoid immediate taxation on the rollover.
- ✔ U.S. withholding and Indian tax liability should be calculated before requesting a distribution.
- ✔ DTAA, foreign tax credit, and applicable retirement-account rules should be reviewed before withdrawing from India.
- ✔ The right 401(k) strategy depends on your age, account balance, tax residency, and long-term plans.
The 401(k) Strategy Most Returning NRIs Should Compare First
Instead of immediately deciding whether to withdraw or keep your entire 401(k), first look at the bigger picture. Your age, U.S. tax status, Indian RNOR/ROR position, plan rules, and whether you need a lump-sum or regular income can all influence the right approach. Before requesting any distribution, compare these five practical options:
| Option | Best fit | Tax/compliance checks before acting |
| Keep the 401(k) invested | You do not need the money soon and your existing plan offers low-cost investment options. | Check whether the plan supports non-resident account holders, India address requirements, beneficiaries, estate-tax exposure, and RMD rules. |
| Direct rollover to a Traditional IRA | You want greater investment flexibility and easier control over your retirement funds. | Prefer a direct rollover to avoid treating the transfer itself as a taxable distribution. |
| Periodic withdrawals | You are over 59½, or an applicable exception may cover the early-distribution penalty, and you prefer regular income. | Review W-8BEN requirements, India-U.S. DTAA Article 20, Indian FTC/Form 67 requirements, and whether scheduled payments are available. |
| RNOR-window withdrawal or conversion review | You have recently returned to India and may still qualify as RNOR. | Review your Indian residential status, source and receipt of income, U.S. withholding, and whether Section 89A/Form 10-EE provisions are relevant. |
| Early lump-sum withdrawal | You have a specific need for the money or deliberately want to simplify your finances. | Calculate ordinary income tax, the potential 10% early-distribution penalty, applicable withholding, and the India tax/FTC impact before requesting the payout. |
What Happens to Your 401(k) When You Move Back to India?
Nothing happens automatically, and that’s the first thing to understand. Your 401(k) does not close, freeze, or force a payout just because you leave the US or lose your visa status. The account stays exactly where it is, with your existing plan administrator (Fidelity, Vanguard, Schwab, or whoever holds it), and continues growing tax-deferred under US law, untouched by your move.
What does change is your relationship to two separate tax systems at once. On the US side, once you’re no longer a US tax resident, the IRS begins treating you as a Non-Resident Alien for future distributions, which changes how withholding is applied. On the India side, your residential status shifts in stages — from NRI, into a transitional RNOR (Resident but Not Ordinarily Resident) window, and eventually into full Resident and Ordinarily Resident (ROR) status, at which point India starts taxing your global income, 401(k) included. The account itself is unaffected by the move; what changes is which country has a claim on money you take out of it, and when.
Should You Withdraw Your 401(k) Before Moving to India?
Don’t Withdraw Just Because You’re Leaving the US
“I’m leaving anyway, so I might as well take the money now” is the single most common reasoning behind a bad 401(k) decision. Leaving the US doesn’t create any tax requirement to withdraw, and a lump-sum cash-out triggers US tax and penalty on the full amount at once, at exactly the point in your life when you have the least ability to offset it against other deductions or credits.
When Withdrawal May Make Sense
Withdrawal can be a reasonable choice if you’re already past 59½ and clear of the early-withdrawal penalty, if your balance is genuinely small enough that the compliance overhead of tracking a foreign account for decades outweighs the benefit of keeping it invested, or if you have a specific, immediate need for the funds a home purchase in India, for instance that makes leaving the money invested abroad impractical.
When Keeping or Rolling Over May Be Better
If you’re years away from retirement, keeping the account invested (or rolling it into an IRA for more control over investment choices) usually wins by a wide margin. It preserves tax-deferred compounding, avoids an immediate five- or six-figure tax hit, and if timed against your RNOR window correctly can even let you convert some of it to a Roth IRA at a lower effective tax cost than you’d face later as a full Indian tax resident.
5 Options for Your 401(k) After Moving to India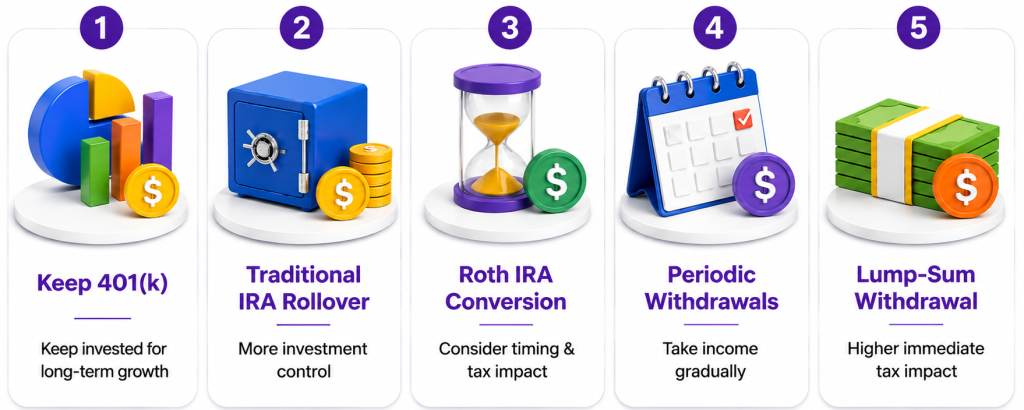
- Leave it invested with your existing US plan administrator, the simplest option; no immediate tax event, continues growing tax-deferred.
- Roll it over into a Traditional IRA — no tax triggered at rollover, but gives you far more control over investments than most employer 401(k) plans allow.
- Convert some or all of it to a Roth IRA — triggers US tax on the converted amount now, but can be strategically timed during your RNOR window when India isn’t taxing that income at all.
- Take periodic (scheduled) withdrawals — smaller, recurring distributions that can qualify for more favourable DTAA treatment than a single lump sum.
- Withdraw the full balance as a lump sum — the fastest option, but also the one that concentrates US tax, the 10% penalty (if applicable), and Indian tax exposure into a single year.
401(k) Withdrawal vs IRA Rollover vs Keeping the Account
| Factor | Lump-Sum Withdrawal | IRA Rollover | Keep 401(k) As-Is |
| Immediate US tax | Yes, on full amount | None (direct rollover) | None |
| 10% early penalty (if under 59½) | Applies to full amount | Not triggered | Not triggered |
| Investment flexibility | N/A — funds withdrawn | Much wider fund choice | Limited to plan’s fund menu |
| India tax exposure | Depends on RNOR/ROR timing | Deferred until later withdrawal | Deferred until later withdrawal |
| Ongoing compliance | None after withdrawal | Annual reporting continues | Annual reporting continues |
| Best suited for | Small balances, immediate need, post-59½ | Long time horizon, wants control | Prefers simplicity, minimal changes |
How to Withdraw a 401(k) From India
Step 1 Check Your Age and Early-Distribution Rules
Before anything else, confirm whether you’re above or below 59½. Distributions taken before that age generally trigger a 10% early-withdrawal penalty on top of regular income tax, unless a specific IRS exception applies (such as certain hardship or separation-related exceptions). This single number changes the entire cost-benefit calculation.
Step 2 Contact the Plan Administrator
Reach out to your 401(k) provider directly and inform them of your change in country of residence. Many custodians have specific procedures and sometimes restrictions for account holders with a non-US address, and some may require you to move the account to an IRA before permitting further changes.
Step 3 Confirm India Address & W-8BEN Requirements
Once you’re no longer a US tax resident, you’ll typically need to file Form W-8BEN with your custodian to certify your foreign status. This determines the default withholding rate applied to your distributions and is also what allows you to potentially claim a reduced treaty rate under the India-US DTAA where applicable. If you’re also juggling other US filing obligations around the same time FBAR, FATCA, or your final resident-year return it helps to have your US tax filing checklist for NRIs sorted out well before your move date, since the W-8BEN switch is just one piece of a larger filing shift.
Step 4 Choose Periodic Withdrawal vs Lump Sum
This decision matters more than most NRIs realise. Under Article 20 of the India-US DTAA, periodic pension-style payments generally receive more favourable treaty treatment than a single lump-sum distribution, which tends to be classified as other income rather than a pension for treaty purposes. Setting up a scheduled withdrawal plan instead of a one-time cash-out can materially change your tax outcome, especially once you’re past your RNOR window.
Step 5 Calculate US & India Tax Before Requesting Payment
Work out your expected US withholding, any early-withdrawal penalty, and your Indian tax exposure based on your current residential status — before you submit the withdrawal request, not after. Once the distribution is paid out, you can’t undo the tax consequences; you can only file returns and claim credits for what already happened.
Step 6 Keep 1099-R and Tax Records
Your plan administrator will issue a Form 1099-R reporting the distribution. Keep this along with withholding statements and, if applicable, your Form 15CA/15CB style documentation and Indian tax filings you’ll need all of it to reconcile the withdrawal on both sides and to support any foreign tax credit claim in India.
How Your US Tax Status Changes After Moving to India
As long as you remain a US citizen or green card holder, the IRS continues to tax your worldwide income regardless of where you live, and you’ll keep filing as normal. But if you were in the US on a work visa and that status lapses when you leave, you typically become a Non-Resident Alien (NRA) for US tax purposes. From that point on, 401(k) distributions to you are generally subject to default NRA withholding — commonly 30% — unless a valid W-8BEN and an applicable treaty provision reduce that rate. This is a meaningfully different withholding regime than what applied while you were a US resident, and it’s worth confirming with your plan administrator exactly which rate they’ll apply before you request a distribution. If any of that US withholding ends up being more than you actually owed once treaty benefits are applied, the mechanics for claiming that back run on the same DTAA and foreign-tax-credit logic covered in this guide to avoiding double taxation as an NRI, even though that piece is framed around property sales rather than retirement accounts.
401(k) Withdrawals During RNOR: What NRIs Should Check
When you return to India, you don’t immediately become a full tax resident with global income exposure. Most returning NRIs first pass through an RNOR window typically the first two to three years back during which India generally does not tax income that accrues or is received outside the country. For many returning NRIs, this creates a genuine opportunity: a 401(k) withdrawal or Roth conversion taken during the RNOR period may avoid Indian tax altogether, even though US tax and any applicable early-withdrawal penalty still apply.
⚠️ Important: RNOR does not automatically make a 401(k) withdrawal tax-free in India. Your specific facts and tax position must be reviewed before taking a distribution.
RNOR eligibility itself depends on your exact travel history and the number of years you were previously non-resident; it isn’t automatic just because you’ve moved back. There are also separate reporting obligations to consider (such as disclosing foreign assets), and provisions like Section 89A of the Income-tax Act, 1961 (renumbered as Section 158 under the Income-tax Act, 2025) exist specifically to address timing mismatches between when US tax law treats 401(k) growth as taxable and when India would otherwise tax it but using this relief correctly requires filing the prescribed election (Form 10-EE under the earlier framework, Form 40 under the current one). This is not a section of the tax code to self-diagnose from a blog post; get your specific RNOR window and eligibility confirmed before you time a withdrawal around it.
What Is the 10% Early Withdrawal Penalty on a 401(k)?
If you take a distribution from your 401(k) before age 59½, the IRS generally applies an additional 10% early-withdrawal penalty on top of the regular income tax owed on the distribution. This applies regardless of where you’re living at the time — moving to India doesn’t exempt you from it. There are specific, narrowly defined exceptions (such as certain separations from service after age 55, disability, or other IRS-recognised circumstances), but “I’m relocating internationally” is not, on its own, one of them. For a large balance, this penalty alone can represent a substantial chunk of your withdrawal, which is exactly why timing and age matter as much as the underlying tax rate.
Should You Convert a 401(k) to a Roth IRA After Moving to India?
This is one of the more powerful and most underused strategies available to returning NRIs, precisely because of the RNOR window. Converting a Traditional 401(k)/IRA balance to a Roth IRA triggers US tax on the converted amount in the year of conversion. If that conversion happens while you’re still within your RNOR period, India generally isn’t taxing that foreign-sourced income at all, meaning you pay US tax once, on your own schedule, and then the funds grow and can eventually be withdrawn tax-free under Roth rules. Do the same conversion after your RNOR window has closed, once you’re a full Indian tax resident, and you could face Indian tax on the same conversion — a very different outcome from the same transaction, based purely on timing. This is worth modelling out with a cross-border tax professional against your specific return date and balance before you decide.
401(k) Withdrawal Example for an NRI Returning to India
Consider Arjun, 45, who moves back to Bengaluru after 15 years in the US and has a $150,000 Traditional 401(k). He’s still two years away from what would be his RNOR window closing.
If Arjun withdraws the full $150,000 as a lump sum immediately: he faces US income tax on the full amount, plus the 10% early-withdrawal penalty since he’s under 59½ potentially reducing his net proceeds by 35–40% before any Indian tax consideration even enters the picture, since a lump sum doesn’t get the same DTAA treatment as periodic payments.
If Arjun instead sets up periodic withdrawals or a partial Roth conversion within his RNOR window, spread across two tax years: he still owes US tax and, if applicable, the early penalty on the amounts withdrawn before 59½, but he avoids Indian tax on those specific amounts during the RNOR period, and periodic payments may qualify for more favourable DTAA treatment than the lump sum would have. The dollar-for-dollar tax bill is meaningfully different not because the account changed, but because the sequencing did.
401(k) Mistakes Returning NRIs Should Avoid
Mistake 1: Withdrawing the Entire 401(k) Immediately
A full lump-sum cash-out concentrates US tax, the 10% penalty, and potential Indian tax exposure into a single year, usually maximising the total tax paid rather than minimising it.
Mistake 2: Ignoring RNOR/ROR Timing
Taking a distribution without confirming exactly where you stand in the NRI → RNOR → ROR timeline means you could be taking a withdrawal at the most expensive possible moment, purely by accident.
Mistake 3: Confusing Withholding With Final Tax Liability
The 20–30% withheld at the time of distribution is not necessarily your final tax bill in either country it’s an upfront collection. Many NRIs assume the withheld amount is the end of the story and skip filing altogether, missing potential refunds or, worse, underreporting what’s actually owed in India.
Mistake 4: Missing Rollover Deadlines
An indirect (60-day) rollover from a 401(k) to an IRA has a strict window miss it, and the amount is treated as a taxable distribution with penalties attached, even if you always intended to roll it over.
Mistake 5: Ignoring India Tax and FTC Records
If your withdrawal does end up taxable in India — whether because it falls outside your RNOR window or because the facts don’t support relief — you’ll need clean records of the US tax already paid to claim a Foreign Tax Credit via Form 67. Sellers who don’t keep 1099-Rs, withholding statements, and payment proof organised often end up paying more in India than they legally need to, simply because they can’t substantiate the US tax already paid. It’s the same discipline that trips up returning NRIs on other cross-border accounts to the NRE/NRO and TDS mechanics that apply once your mutual fund folios are reclassified follow a similar pattern of upfront withholding that only gets settled correctly if you keep the paperwork.
Final Verdict — Should You Withdraw Your 401(k) Before Moving to India?
For most returning NRIs, the answer is: not immediately, and not as a lump sum. The account survives the move untouched, and the real decision isn’t whether to eventually access the money it’s when and how, so that US withholding, the 10% early penalty, and India’s RNOR window all work in your favour instead of against each other. A small 401(k) with an urgent, immediate use for the cash is a reasonable exception. Everything else benefits from a plan built around your specific age, balance, and return timeline — ideally worked out with a cross-border tax advisor before you request a single distribution, not after the 1099-R has already arrived.
Getting your broader return-to-India financial picture in order alongside this decision helps too for instance, understanding how to hold your foreign currency savings once you’re back through an RFC account instead of converting everything to rupees immediately can prevent an unrelated but equally costly mistake at the same time you’re making your 401(k) decision.
Conclusion
Your 401(k) is one of the few pieces of your US financial life that doesn’t force a decision the moment you board the flight back to India which is exactly why it deserves more planning, not less. The gap between a rushed lump-sum withdrawal and a sequenced strategy built around your RNOR window can be the difference between keeping most of what you saved and handing a third of it away in avoidable tax and penalties.
Disclaimer
The content published on NriTaxs is intended for informational purposes only and does not constitute legal, tax, or financial advice. Readers are encouraged to consult qualified professionals before making any decisions based on the information provided.
Related Articles