If you’re an NRI trying to build long-term wealth in India, you’ve probably had this exact debate with yourself: put money into a ULIP that also gives you life cover, or stick to a mutual fund that’s simpler and more flexible? Both are sold as “long-term wealth builders,” both invest in the same kind of markets, and both come with their own tax rules , which only makes the choice more confusing. This guide breaks down ULIP vs Mutual Fund for NRIs, how each one is taxed in 2026, and which one fits better depending on what you’re actually trying to achieve.
Key Takeaways
- ✔ NRIs can generally invest in both ULIPs and mutual funds in India.
- ✔ ULIPs combine life insurance with market-linked investments, while mutual funds focus mainly on investment growth.
- ✔ ULIPs have a 5-year lock-in, whereas most mutual funds offer greater liquidity.
- ✔ ULIP charges are more layered, while mutual fund costs are generally easier to compare.
- ✔ NRIs should understand capital gains tax, TDS and DTAA benefits before investing.
- ✔ The better option depends on your financial goals, investment period, insurance needs and tax situation.
- ✔ For pure long-term wealth creation, mutual funds may offer more flexibility, while ULIPs can suit investors seeking insurance and investment together.
What Is a ULIP?
A ULIP, or Unit Linked Insurance Plan, is a hybrid product that combines life insurance with market-linked investing. Part of your premium buys life cover, and the rest is invested in equity, debt, or a mix of both, based on the fund option you choose. It’s issued by an insurance company, not a mutual fund house.
Key Features of ULIPs for NRIs
- Combines life insurance cover with market-linked investment growth in a single policy.
- Comes with a mandatory five-year lock-in period before any withdrawal is allowed.
- Lets you switch between equity and debt funds within the same policy.
- Premiums and charges are typically payable through an NRE or NRO account.
How Does a ULIP Work?
- You pay a regular or single premium, and the insurer deducts charges before investing the remaining amount.
- The remaining premium is allocated to fund options you select, based on your risk appetite and goals.
- Your money grows or falls in value along with the performance of the underlying funds chosen.
- On maturity or in the event of death, the accumulated fund value or sum assured is paid out.
Can NRIs Buy ULIPs in India?
Yes, NRIs can generally buy ULIPs in India, subject to applicable FEMA rules, insurer eligibility requirements, KYC and other regulatory conditions. NRIs can purchase ULIPs from eligible Indian insurance companies using permitted banking channels, such as NRE or NRO accounts, depending on the policy and payment arrangement.
Before investing, NRIs should check the ULIP’s lock-in period, charges, tax treatment, repatriation rules and their country-of-residence tax obligations. For NRIs, the tax outcome can differ depending on the policy structure and applicable conditions.
What Is a Mutual Fund?
A mutual fund is an investment option where money from many investors is collected and invested in assets such as stocks, bonds, or other securities. A professional fund manager manages these investments based on the fund’s objective. Investors can choose different types of mutual funds depending on their risk and financial goals. NRIs can also invest in Indian mutual funds, subject to KYC, FEMA, FATCA, and applicable tax rules. Mutual funds generally offer more flexibility and liquidity than ULIPs.
Key Features of Mutual Funds for NRIs
- Pure investment product with no bundled insurance cover attached to it.
- Wide choice of fund categories equity, debt, hybrid, based on your goals.
- Generally no lock-in, except for ELSS funds and a few solution-oriented schemes.
- Can be started or exited through NRE or NRO-linked accounts easily.
How Do Mutual Funds Work for NRIs?
- You invest a lump sum or start a SIP linked to your NRE or NRO bank account.
- The fund manager invests pooled money across securities matching the scheme’s stated objective.
- Your investment value moves up or down daily, tracked through the fund’s NAV.
- You redeem units whenever needed, subject to exit load and applicable capital gains tax.
Can NRIs Invest in Mutual Funds in India?
Yes, NRIs can invest in mutual funds in India, subject to applicable FEMA, KYC, and tax regulations. They can invest through NRE or NRO accounts, depending on their investment and repatriation requirements. Before investing, NRIs generally need to complete KYC and provide required documents, including PAN and FATCA details. However, some mutual fund houses may have restrictions for investors residing in certain countries. NRIs should also understand TDS, capital gains tax, and DTAA benefits before investing.
ULIP vs Mutual Fund — Detailed Comparison for NRIs
ULIP vs Mutual Fund for Returns
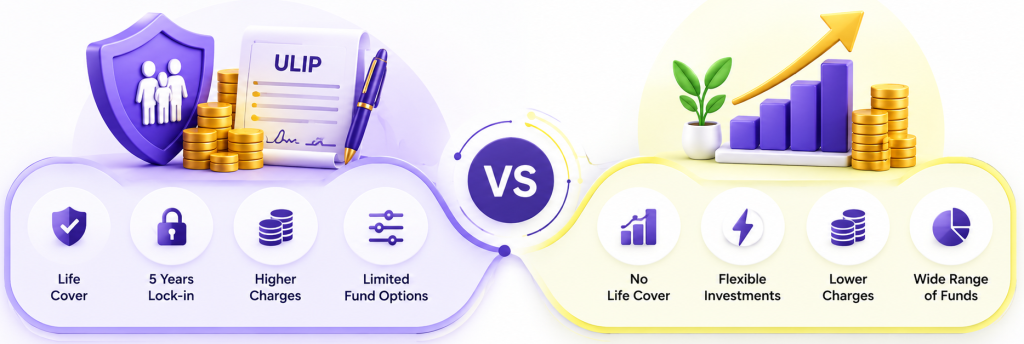
Mutual funds generally deliver better long-term returns than ULIPs, mainly because ULIPs carry insurance-related deductions that reduce the actual amount going into investment, especially in the early years. Over a 10–15 year horizon, a well-chosen equity mutual fund tends to outperform an equivalent ULIP purely because more of your money is working in the market from day one.
ULIP vs Mutual Fund: Charges and Costs
ULIPs typically carry premium allocation charges, mortality charges, fund management charges, and policy administration charges several layers stacked on top of each other. Mutual funds charge a single expense ratio, which is usually lower overall and far easier to compare across schemes since it’s the only cost you’re really tracking.
ULIP vs Mutual Fund: Lock-in and Liquidity
This is genuinely the part that matters most for an NRI’s decision. A ULIP locks your money in for five years, no exceptions, even in a financial emergency, you cannot withdraw before that period ends without losing significant value. Mutual funds, apart from ELSS (which has a three-year lock-in) and a handful of solution-oriented schemes, have no lock-in at all, you can redeem within a day or two whenever you need the money. If you’re an NRI who might need to move funds back for a property purchase, a family emergency, or a change in your country of residence, that flexibility matters far more than it sounds on paper. A ULIP essentially asks you to commit money you won’t touch for half a decade; a mutual fund never asks that of you unless you choose ELSS specifically for the tax deduction.
ULIP vs Mutual Fund — Key Differences
| Factor | ULIP | Mutual Fund |
| Nature | Insurance + investment combined | Pure investment product |
| Lock-in | Mandatory 5 years | None, except ELSS (3 years) |
| Charges | Multiple layers — allocation, mortality, fund management, admin | Single expense ratio |
| Liquidity | Low during lock-in period | High, redeemable anytime |
| Fund switching | Usually tax-free within the policy | Triggers capital gains tax on switch |
| Life cover | Included | Not included |
ULIP vs Mutual Fund Taxation for NRIs in 2026
ULIP Taxation for NRIs
If your ULIP was issued on or after February 1, 2021 and your total annual premium is up to ₹2.5 lakh, the maturity proceeds remain fully tax-exempt under Section 10(10D). Cross that ₹2.5 lakh annual premium mark, and the gains are taxed as capital gains instead, 12.5% for long-term gains (held over 12 months) and 20% for short-term gains, similar to equity mutual funds. TDS is deducted on the taxable portion before the payout reaches you, so it’s worth checking your policy’s premium structure before assuming the entire maturity amount is tax-free.
Mutual Fund Taxation for NRIs
For equity mutual funds, short-term gains (held 12 months or less) are taxed at 20%, and long-term gains (held over 12 months) are taxed at 12.5% on anything above ₹1.25 lakh in a financial year. Debt mutual funds bought on or after April 1, 2023 are taxed at your applicable slab rate regardless of how long you’ve held them, with no separate long-term benefit. Unlike resident investors, NRIs face TDS deducted by the AMC at the time of redemption itself, this is a key difference worth understanding properly through a guide on what actually changes with your mutual fund investments once you become an NRI, since the TDS and repatriation mechanics catch a lot of people off guard.
ULIP vs Mutual Fund for NRI: Which Is Better for Long-Term Investment?
Choose ULIP If:
- You want life insurance cover bundled together with a long-term investment plan.
- You’re comfortable locking your money away for a minimum of five years.
- You want to switch between equity and debt without triggering tax each time.
- You’re saving for a distant goal like retirement and won’t need early access.
- You already have separate term insurance and want ULIP purely as an add-on goal.
Choose Mutual Funds If:
- You want flexibility to redeem your investment whenever you actually need it.
- You prefer transparent, lower-cost investing without multiple layered charges involved.
- You already hold separate term insurance and don’t need bundled life cover.
- You want a wider choice of fund categories to match different financial goals.
- You value simplicity in tracking returns, costs, and your overall tax liability.
Common Mistakes NRIs Make When Choosing ULIPs or Mutual Funds
- Buying a ULIP mainly for tax saving without checking if the ₹2.5 lakh premium limit is being crossed.
- Ignoring the five-year lock-in and then needing that money urgently during an emergency abroad.
- Not updating KYC and bank account details after moving abroad, which can freeze future transactions — a step covered in detail in this guide on completing mutual fund KYC for NRIs entirely online.
- Assuming ULIP charges are similar to mutual fund expense ratios, when they’re usually significantly higher.
- Never checking how currency movement and repatriation rules affect the real return on either investment, a factor explained in this guide on managing currency risk in NRI investments.
Conclusion
There’s no single right answer here — a ULIP makes sense if you genuinely want insurance and investment bundled together and don’t mind the five-year lock-in, while a mutual fund wins on cost, flexibility, and transparency for most long-term NRI investors. If you already have term insurance separately, mutual funds usually come out ahead for pure wealth building. Match the product to your actual goal and timeline, not the pitch, and you’ll rarely go wrong.
Disclaimer
The content published on NriTaxs is intended for informational purposes only and does not constitute legal, tax, or financial advice. Readers are encouraged to consult qualified professionals before making any decisions based on the information provided.
Related Articles