If you run a business in India from abroad, the tax audit form you have used for years is changing. Form 26 is the new tax audit report under the Income-tax Act, 2025. It brings Forms 3CA, 3CB and 3CD into one single form. But there is a catch: it does not apply to every return you file today. For FY 2025-26, the old forms still work, and the audit-case ITR deadline is 31 October 2026. This guide explains what Form 26 is, how its four parts work, what changed from Form 3CD, who needs a tax audit, and what NRI business owners should do now. Read it before you speak to your CA, so you know what to ask.
Quick Answer
Form 26 is the new tax audit report under the Income-tax Act, 2025. It replaces Forms 3CA, 3CB and 3CD from tax year 2026-27. For FY 2025-26 (AY 2026-27), including the 31 October 2026 audit-case deadline, you still use the old forms. An NRI with Indian business turnover above the audit limit needs a chartered accountant to prepare the report.
What Is Form 26 and Why Was It Introduced?
Form 26 is the tax audit report and statement of particulars under Section 63 of the Income-tax Act, 2025, read with Rule 47 of the Income-tax Rules, 2026. It replaces Forms 3CA, 3CB and 3CD. A chartered accountant uses it to report your business accounts and tax details for a tax year.
The government introduced it for four main reasons:
- One form instead of three: Earlier, you dealt with Form 3CA or 3CB plus Form 3CD. A single form removes repeated details and makes the process easier to follow.
- Better match with the ITR: Audit clauses are now aligned with the return of income, so numbers in the audit report and your ITR stay consistent.
- Structured data: Drop-downs, auto-filled fields and standard formats make the report easier for the tax department to check and compare.
- New items reported: Capital receipts, deemed incomes and detailed TDS/TCS figures now have their own fields instead of general remarks.
Structure of Form 26: Four Parts Explained
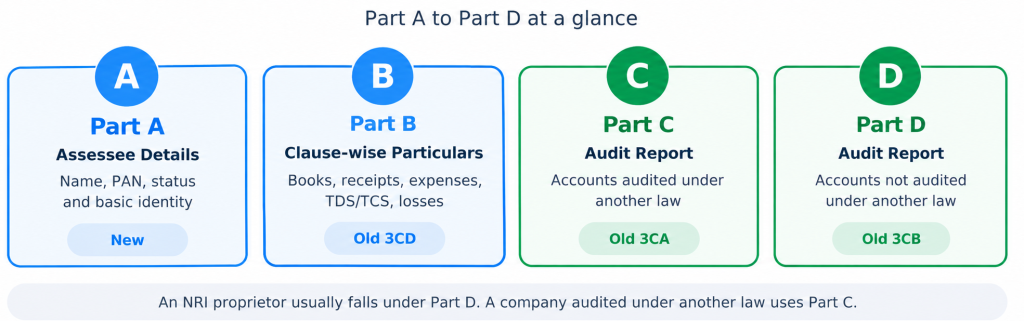
Form 26 has four parts. Some older blogs say five parts, but the notified structure, as described by most tax sources, is Part A to Part D.
Part A: Details of the Assessee
This part holds basic identity details such as your name, PAN, status (individual, firm, company and so on) and address. Your CA fills it from your PAN and registration records.
Part B: Clause-wise Particulars
This is the old Form 3CD in a new shape. It covers general business information, books of account and method of accounting, receipts and income, expenses, prior-period items, and losses, depreciation and deductions. It also carries the detailed TDS/TCS clauses.
Part C: Audit Report Where Accounts Are Audited Under Another Law
This part replaces Form 3CA. It applies when your accounts are already audited under another law, for example an Indian company audited under the Companies Act.
Part D: Audit Report Where Accounts Are Not Audited Under Another Law
This part replaces Form 3CB. It applies when the tax audit is the only audit. An NRI who runs a proprietorship in India usually falls here.
Old Forms vs Form 26: What Actually Changed
Form 26 is not just a renumbered Form 3CD. It changes how information is collected and reported. Even the familiar Form 26AS now has a new number, Form 168. You can compare it with your AIS using our guide on AIS vs Form 26AS mismatch for NRIs.
| Point | Old Forms (3CA/3CB + 3CD) | New Form 26 |
| Number of forms | Two forms (3CA or 3CB, plus 3CD) | One single form |
| Legal basis | Section 44AB, Rule 6G (1961 Act) | Section 63, Rule 47 (2025 Act) |
| Clauses | 44 clauses in Form 3CD | About 55 clauses |
| Format | Mostly narrative clause-wise answers | Structured data, drop-downs, auto-filled fields |
| TDS/TCS reporting | One clause (clause 34) | Three clauses (49, 50 and 51) with exact transaction count and amount |
| Income outside P&L | Limited reporting | Expanded: deemed incomes, capital receipts, buy-back, subsidies |
| GST details | Breakup of expenses by GST registration | Limited GST reporting |
| Auditor details | General | Mandatory auditor identification details |
| Applies to | FY 2025-26 and earlier | Tax year 2026-27 onwards |
Note: clause numbers and counts come from published rules and expert commentary. Check the final notified form on incometax.gov.in before quoting any specific clause.
Which Form Applies to You: 3CA/3CB/3CD or Form 26?
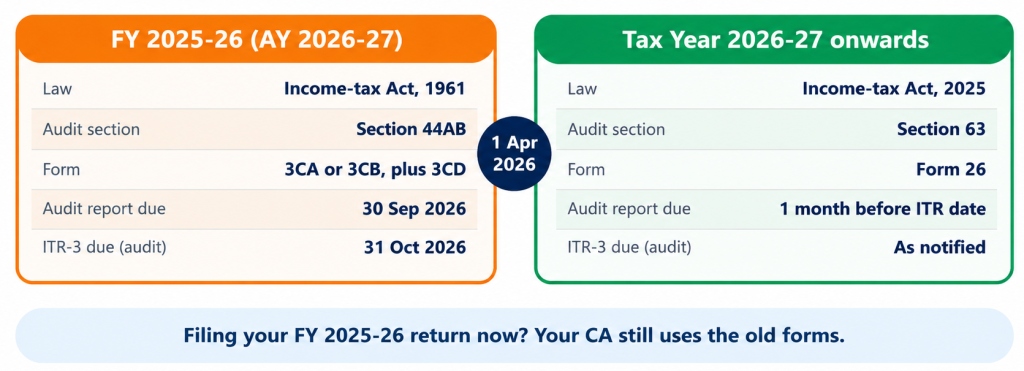
The rule is simple: the income period decides the form, not the date you file.
| Income period | Governing law | Audit section | Form to use |
| FY 2025-26 (AY 2026-27) | Income-tax Act, 1961 | Section 44AB | Form 3CA or 3CB, plus 3CD |
| Tax year 2026-27 (1 April 2026 to 31 March 2027) | Income-tax Act, 2025 | Section 63 | Form 26 |
So if you are filing your ITR for FY 2025-26 right now, your CA will still use the old forms. Form 26 becomes relevant for the business year that started on 1 April 2026.
Who Needs a Tax Audit?
Tax audit is not for every business. It depends on your turnover or receipts and on how you computed your income. The limits below are from the current framework and are expected to carry over, so confirm them with your CA.
- Businesses:- A tax audit applies when business turnover is above ₹1 crore in a year. The limit rises to ₹10 crore if cash receipts and cash payments are each 5% or less of the total.
- Professionals:- A professional, such as a consultant, architect or freelancer, needs a tax audit when gross receipts are above ₹50 lakh in a year.
- Presumptive Taxation Opt-Outs:- A tax audit can also apply when you opt out of a presumptive scheme, declare profit below the deemed rate, and your total income is above the basic exemption limit. For NRIs, one point matters here: the CBDT validation rules for ITR-3 say presumptive income under Section 44AD cannot be disclosed by a non-resident. So for most NRIs, the turnover and receipts test is what decides the audit.
Does an NRI Business Need a Tax Audit?
Yes, if the Indian business turnover or receipts cross the limits above. The turnover is counted for the business carried on in India, not your income abroad. If you have business income in India, you also file ITR-3. Our guide on the ITR form for NRI business income explains how to pick the right form.
What the New Form Asks from NRI Business Owners
Your CA does the filling, but the information comes from you. Here is what to keep ready.
Books of Accounts
Form 26 asks which method of accounting you follow (cash or mercantile) and what books you maintain. Keep your ledger, bank statements and invoices complete and in order.
GST Reconciliation
If you are GST-registered, match your GST turnover with your books and your ITR. Mismatches are easy for the department to spot.
TDS Reporting
The new form asks for all TANs, whether TDS/TCS applied, and the exact number and value of transactions where tax was not deducted or deposited. This is a major change from the old single clause. For the basics, read our guide on TDS on NRI business income and the refund process.
Foreign Remittances and Related-Party Details
If your Indian business pays money abroad or deals with related parties, keep agreements, invoices and payment records ready. Your CA may need them for related-party and remittance-related reporting.
How Form 26 Is Filed: Auditor and Assessee Steps
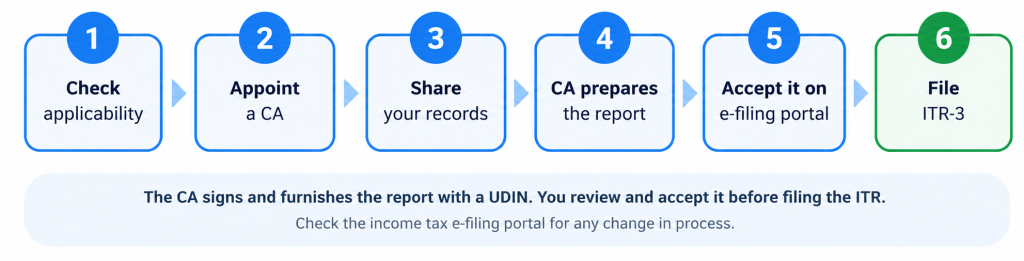
The CA furnishes the report, but you also have a role. The steps below follow the current portal practice, so check the e-filing portal for any change.
- Check applicability. Compare your turnover or receipts with the audit limits.
- Appoint a chartered accountant. Do this early, not near the due date.
- Share your records. Give books, bank statements, GST returns and TDS details.
- CA prepares the report. The CA completes Part A, Part B and Part C or Part D, and signs with a UDIN.
- Review and accept. The report is furnished on the income tax e-filing portal, and you get a request to accept it.
- File your ITR-3. Only after the audit report is in place.
Due Dates for Tax Audit and ITR (Audit Cases)
| Item | FY 2025-26 (AY 2026-27) | Tax year 2026-27 (Form 26) |
| Tax audit report | 30 September 2026 | One month before the ITR due date |
| ITR-3 (audit cases) | 31 October 2026 | As notified under the 2025 Act |
| ITR-3 (non-audit cases) | 31 August 2026 | As notified under the 2025 Act |
| Form used | 3CA/3CB + 3CD | Form 26 |
The 30 September 2026 audit report date has already passed, and the 31 October 2026 ITR date is only a few days away. If your audit is still pending, speak to your CA immediately about the next steps and the cost of delay.
Penalty for Missing the Tax Audit
Under the 1961 Act (Section 271B), the penalty for not getting accounts audited, or not furnishing the report on time, is 0.5% of turnover or gross receipts, with a maximum of ₹1,50,000. The penalty may not apply if you show a reasonable cause. For tax year 2026-27, the 2025 Act has a similar provision under a new section number, so confirm the exact section and amount in the final law. A missed audit can also lead to notices and delays in filing a complete return.
How Businesses Should Prepare for the Transition
- Keep books updated every month. Do not wait until year-end to write accounts.
- Check TDS credits early. Match your credits in Form 168 (earlier Form 26AS) and AIS.
- Collect remittance papers. Keep documents for payments abroad. Our guide on Form 145 and 146 for NRIs explains the new numbers for 15CA/15CB.
- Appoint your CA early. More data fields mean more preparation time.
- Track new items. Note capital receipts, subsidies, buy-back proceeds and other deemed incomes during the year.
Clause Mapping: Old Form 3CD to Form 26 Part B
The table below shows mappings confirmed in published commentary. Some entries are based on the draft form, so match them with the final notified Form 26 before relying on them.
| Old Form 3CD clause | Subject | Where it sits in Form 26 | What changed |
| Clause 4 | Status of the assessee | Part A | Moved to the assessee details part |
| Clause 10 | Change in nature of business | Part B, general information | Now reported through a schedule |
| Clause 16 | Amounts not credited to the P&L | Clauses 20 and 21 (draft) | Wider list, including buy-back, subsidies and business trust income |
| Clause 34 | TDS/TCS compliance | Clauses 49, 50 and 51 | One clause became three; exact transaction count and value required |
For the complete clause-by-clause list, use the official mapping on the income tax website or the ICAI mapping document.
Common Mistakes NRIs Make
- Using Form 26 for FY 2025-26. The old forms still apply to that year.
- Skipping audit because the owner lives abroad. Indian turnover decides, not where you live.
- Relying on Section 44AD. It is not available to non-residents in ITR-3.
- Filing ITR before the audit report. The report must be in place first.
- Ignoring GST mismatches. GST turnover should match books and ITR.
- Missing TDS details. The new form asks for exact counts and values.
Conclusion
Form 26 simplifies tax audit reporting by replacing three forms with one, but it asks for more structured detail. For FY 2025-26, stay with the old forms and meet the 31 October 2026 deadline. For the business year that started on 1 April 2026, prepare your books, TDS and GST records now, and appoint your CA early.
Disclaimer
The content published on NriTaxs is intended for informational purposes only and does not constitute legal, tax, or financial advice. Readers are encouraged to consult qualified professionals before making any decisions based on the information provided.
Related Articles